
Quick reality check
Riders and couriers know cash flow isn’t always steady — especially after a shift cancelled or a vehicle repair. That’s where didi prestamos comes into play for many in Latin America, offering fast access to small loans from within an app they already use. Since the COVID-19 shock in 2020, more gig workers in places like Mexico City turned to digital lending for emergency support; that moment changed expectations about speed and convenience for creditos en linea.
What DiDi Finanzas actually does for you
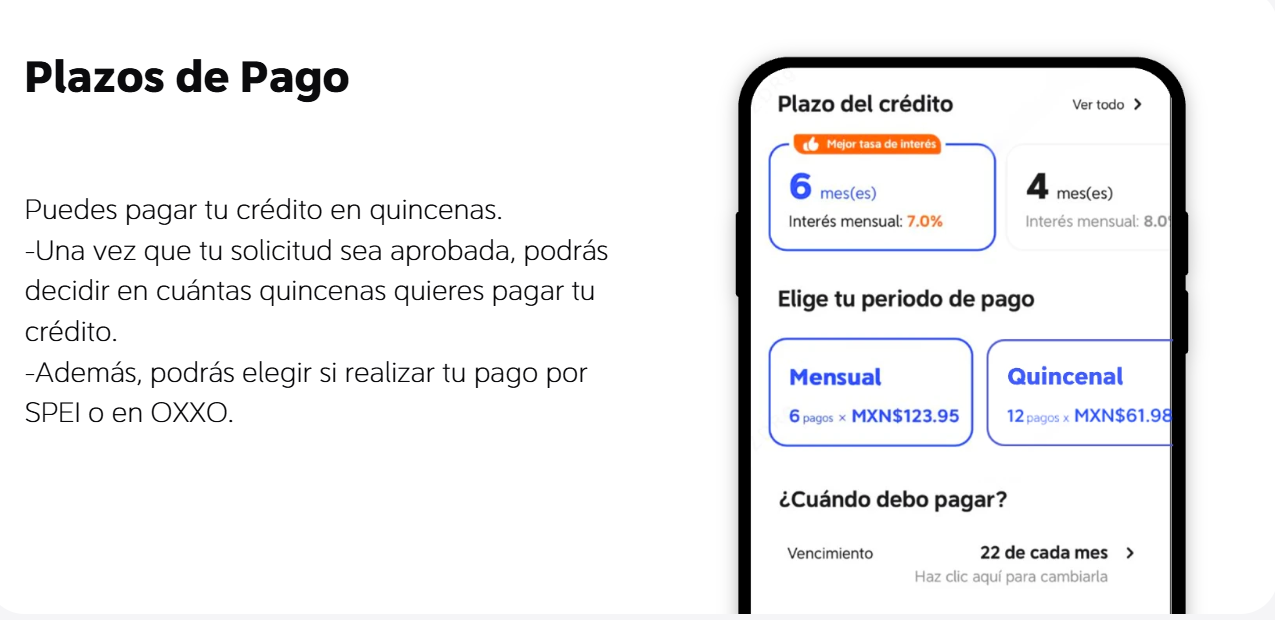
Think of it as a microcredit lane inside a familiar platform. DiDi Finanzas links loan origination and repayments to your driver account, simplifying verification and reducing friction. The app can show estimated interest rate, repayment term, and an upfront APR so you know the cost before you accept. For someone juggling daily fares, those features matter more than marketing copy — they lower uncertainty and time spent on paperwork.
Step-by-step: How to use the in-app loan without surprises
Start with the basics: check the loan amount, APR, and repayment schedule. Then confirm KYC info and any soft credit inquiries that affect your credit score. Typical flow:
– Select amount and term.
– Review APR and total repayment.
– Complete quick underwriting (often automated) and accept funds into your wallet.
Keep receipts and screenshots of the agreement — fintech systems are fast, but documentation keeps you protected if something changes.
Common mistakes to avoid
Many users accept the first offer without comparing terms — that raises the effective cost. Others miss the effect of overlapping repayments: two loans with similar repayment dates can choke cash flow. Also, avoid misunderstanding amortization: the early payments often cover interest, so principal falls slowly. — It’s easy to overlook that until the next month’s balance arrives.
Alternatives worth considering
If a DiDi-integrated loan isn’t ideal, traditional options include bank overdrafts, prepaid credit lines, or rival fintech apps. Banks can offer lower interest rate for established customers but require longer approval and more documentation. Peer-to-peer platforms sometimes provide flexible terms, yet underwriting can be stricter. Compare total cost (fees + APR) and processing time before choosing.
How to judge a good in-app loan — quick checklist
Use these metrics when picking an option: clear APR disclosure, reasonable underwriting speed, and transparent fees. Add two more practical checks: alignment of repayment dates with your pay rhythm, and the option to prepay without penalty. These points cut through buzzwords and show real value.
Real-world anchor and credibility
Across Latin America, regulators and gig platforms responded to pandemic-era demand by improving KYC flows and fraud detection; those changes made instant underwriting more reliable for drivers. My own time advising small driver collectives in Mexico City showed that clear APRs and predictable repayment terms reduce default stress and stabilize income — practical proof that simple transparency matters.
Three golden rules before you accept a loan
1) Verify total cost: check APR plus all fees, not just the headline rate. 2) Match repayment dates to your cash cycle to avoid rollover. 3) Keep emergency savings separate — use credit for gaps, not habitual expenses. These three metrics tell you if a loan is helpful or a trap.
DiDi Finanzas fits where speed, familiar interfaces, and driver-centric features meet — it’s a practical solution for many on-the-road people who need fast, transparent support. Trust the numbers, guard your cash flow, and choose tools that make daily work smoother — quick, clear, and fair.