
The problem unfolding now
The cost of living in Mexico has shifted like a cityscape under neon clouds: prices climb, wages lag, and everyday budgeting feels jittery. Consumers in Mexico City and beyond face tighter margins after the global inflation surge tied to supply shocks and monetary shifts—Banco de México has responded with policy moves that shifted borrowing costs nationwide. Against that backdrop, tools that let you spread payments without losing control matter. Enter didi finanzas, a platform that frames installment buying as a deliberate saving tactic rather than an impulse trap.
Why installment buying can be a defensive play
Installment plans shift timing, not value. Properly used, they preserve cashflow and let you avoid liquidating savings when prices spike. Think of an installment plan as a calibrated cadence: a clear repayment schedule, transparent interest rate or APR, and predictable entries in your digital wallet. When structured with low fees, buying in installments prevents short-term debt from ballooning into chronic liability. The key is discipline—align purchases with income cycles and track outstanding balances so your credit score stays intact.
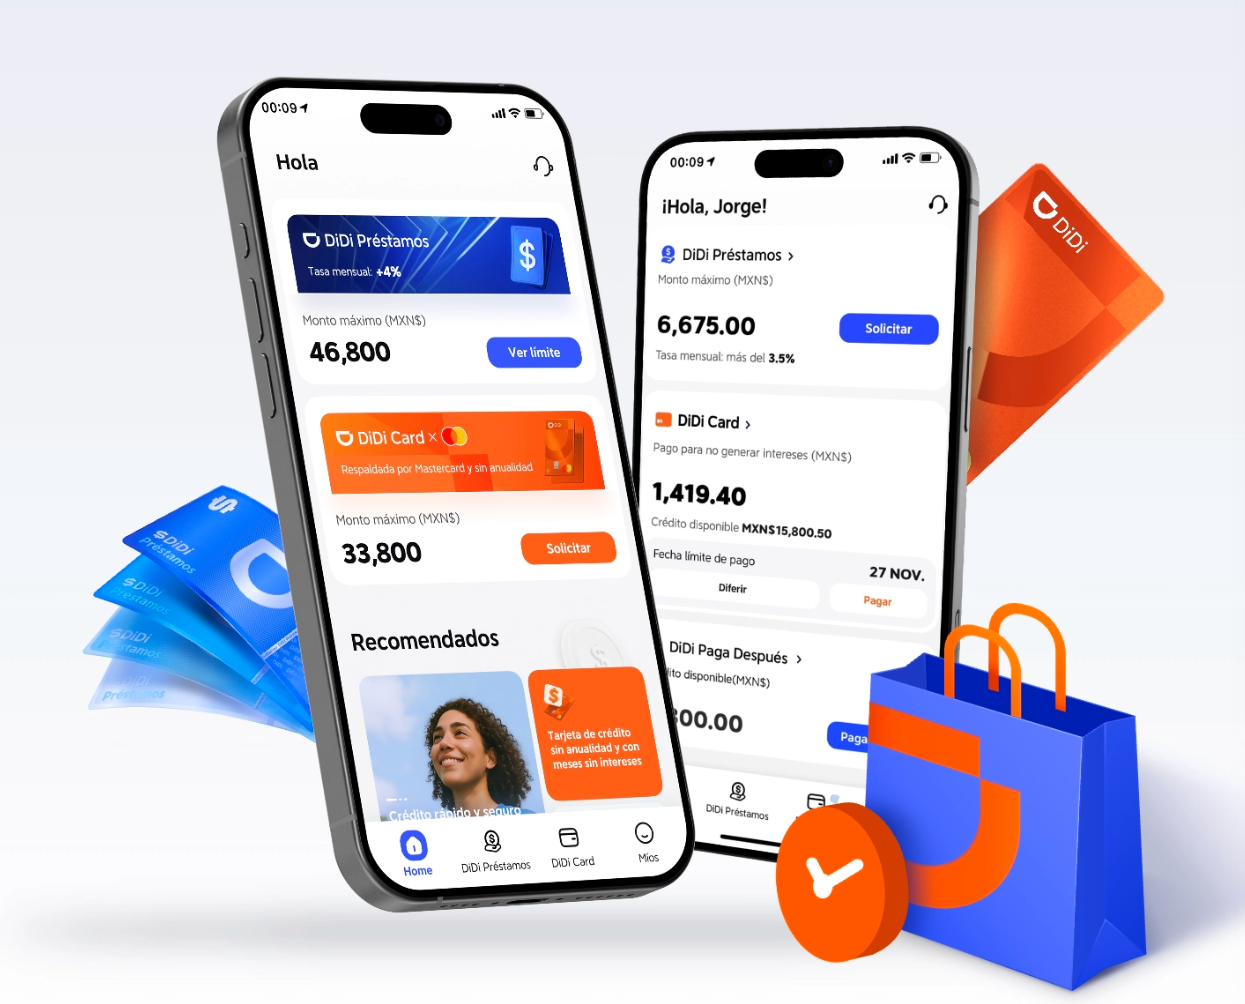
How DiDi Finanzas translates strategy into action
The platform translates speculative strategy into routine habit. Its interface presents the total cost, per-installment amount, and the effective APR—so choices are visible before you commit. For people juggling irregular income, the app recommends staggered repayment schedules that match payroll dates. Features like automatic debit, reminders, and a consolidated view of open installments reduce cognitive load. Using the didi finanzas app turns an abstract plan into a ledger you actually follow; the result is steadier cashflow and fewer surprise fees.
Practical steps to use installments without getting burned
Start with essentials: prioritize appliances or tools that extend earning potential or cut recurring costs. Second, compare offers on three axes—total cost, repayment length, and late-fee structure. Third, avoid overlapping repayments that create a debt cascade. Keep the list short:- Calculate net monthly impact before approving any installment.- Favor zero- or low-interest plans for predictable purchases.- Reserve one buffer month in your budget for unexpected shortfalls.These actions keep installment buying a tactical lever rather than a risk amplifier—small adjustments, big resilience.
Common mistakes and viable alternatives
People often misuse installments for nonessential consumption, confusing convenience with necessity—this is where rent-to-own traps appear. Another frequent error is underestimating fees when a plan advertises “no interest” but hides processing charges. Alternatives include short-term micro-savings (set aside a small portion each week), using a low-cost line of credit for emergencies, or choosing layaway where you control release of funds. Each alternative trades immediacy for lower total cost—pick the one that matches your cashflow profile and risk tolerance.
Real-world anchor and credibility
The strategy reflects observed behavior across Mexican urban centers where digital payments and buy-now-pay-later products gained traction after 2020. Platforms that emphasize clarity and automated tracking report higher on-time repayment rates—this aligns with fintech industry findings and with what users report in Mexico City neighborhoods. Practical experience shows that when installment products are transparent and paired with simple budgeting tools, households avoid debt stress and preserve savings.
Three golden rules for choosing the right approach
1) Prioritize transparency: choose plans that show the total cost and APR up front. 2) Match term to purpose: short terms for essentials, longer terms only for durable, income-generating goods. 3) Keep a liquidity buffer equal to at least one installment cycle to avoid rollovers. These metrics let you evaluate offers quickly and prevent costly surprises. Closing thought: smart installments are a tool—use them with discipline and they become a stabilizer, not a liability. DiDi Finanzas. A small fragment of calm for a noisy ledger.